Advertisement






The Gulf conflict has disrupted global supply chains, pushed...
REITs have changed the way commercial real estate is owned a...
What really powers the cloud? Behind every Google search, A...
What really powers the cloud? Behind every Google search, A...
Luxury real estate is one of the most talked-about segments ...
Dubai developers have largely maintained off-plan launch prices through 2026 despite changes in sales volumes and project absorption, according to a market analysis by fäm Properties released on September 30. Of 717 off-plan projects launched since July 2023 with sufficient registered sales data, 44 projects, or 6%, have reduced prices by at least 5% since the end of February, while 28 projects, or 4%, are currently priced below their original launch levels. The analysis found a stronger relationship between pricing and sales absorption, particularly among projects launched since 2025. While registered developer apartment sales fell 6% year-on-year during the first eight months of 2026, studio transactions rose 26%, supported significantly by Dubai South, where studio sales increased 185%.
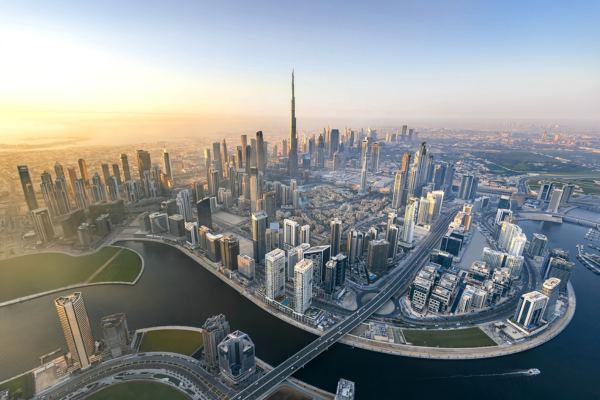
Dubai’s developers have largely kept off-plan prices unchanged during 2026 despite adjustments in sales volumes and absorption rates, with project pricing increasingly influencing the pace at which units are sold, according to a market analysis by fäm Properties released on September 30.
The analysis covered 717 off-plan projects launched since July 2023 that had sufficient registered sales to assess their performance. Of these, 44 projects, equivalent to 6%, had reduced prices by 5% or more since the end of February. Only 28 projects, or 4%, were selling below their original launch prices.
The first price reductions identified in the analysis occurred in June 2026 or later. According to fäm Properties, pricing changes have been influenced by conditions within individual local markets, while developers have generally avoided broad reductions to their headline launch prices.
The relationship between pricing and absorption was more evident among projects launched since 2025. Across 574 such projects, the median project was priced 4.2% above the median price for its respective area and had sold 73.8% of its units. Projects priced at least 20% above their local area median recorded median sales absorption of 60%.
Firas Al Msaddi, founder and CEO of fäm Properties, said pricing was increasingly determining the pace at which projects were selling out. He noted that developers had generally been reluctant to reduce headline prices, making a project's positioning against comparable properties more significant to its sales performance.
Registered developer apartment sales during the first eight months of 2026 totalled 62,147, representing a 6% decline from the corresponding period in 2025. The adjustment was not uniform across apartment categories, however, with studios recording an increase while larger apartment segments registered declines.
Studio transactions rose 26% to 21,728 during the period. In contrast, sales of one-bedroom apartments declined 18%, while two-bedroom and three-bedroom apartment sales fell 16% and 13%, respectively.
Dubai South was a significant contributor to the increase in studio transactions, recording an 185% rise in sales to 11,147 during the first eight months of 2026.
According to Al Msaddi, the market adjustment was more apparent in sales volumes and absorption rates than in widespread reductions to launch prices. He said more than nine in 10 projects covered by the analysis had retained their original launch pricing.
The analysis also highlighted the importance of pricing relative to competing projects as developers operate across an expanding range of locations and developments. Projects positioned closer to prevailing market prices recorded higher median sales absorption than those carrying a substantial premium over their respective local markets.
17th Nov, 2026
15th Nov, 2026
14th Nov, 2026

2nd Nov, 2026
30th Oct, 2026
Advertisement








 Facebook
 Whatsapp

