Advertisement






The Gulf conflict has disrupted global supply chains, pushed...
REITs have changed the way commercial real estate is owned a...
What really powers the cloud? Behind every Google search, A...
What really powers the cloud? Behind every Google search, A...
Luxury real estate is one of the most talked-about segments ...
UK house prices recorded their first annual decline in nearly three years in August, according to the latest Lloyds House Price Index. Prices fell 0.4% from a year earlier and declined 0.2% during the month, against economists’ expectations for growth. The average UK property price stood at £298,468. Higher borrowing costs, inflation concerns and wider economic uncertainty have made both buyers and sellers more cautious. While some buyers are delaying purchases, homeowners have generally been reluctant to reduce asking prices sharply. The figures also show a growing difference between the performance of northern regions and southern England.
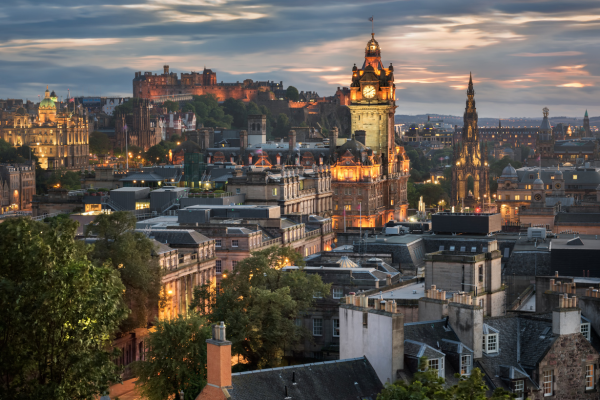
British house prices fell on an annual basis in August for the first time since November 2023, according to data from Lloyds, as higher borrowing costs and economic uncertainty weighed on activity in the housing market.
The Lloyds House Price Index showed that prices were 0.4% lower than a year earlier, compared with the 0.2% annual increase economists had expected in a Reuters poll. On a monthly basis, prices declined 0.2% in August, while July's initial 0.1% increase was revised to a 0.1% fall. The average UK house price stood at £298,468 in August.
The latest figures point to a more cautious housing market as borrowing costs remain elevated. Lloyds said global developments have affected inflation and borrowing costs, creating greater uncertainty for households considering a property purchase.
Andrew Asaam, mortgages director at Lloyds, said homeowners were not rushing to cut prices. Instead, more sellers were choosing to wait rather than accept offers they considered too low, while buyers were also holding back until there was greater clarity on market conditions.
The annual decline was weaker than economists had anticipated. The Reuters poll had pointed to a 0.2% annual increase and a 0.1% monthly rise for August. The latest reading therefore indicates that price growth has slowed more sharply than expected.
The trend has also been influenced by mortgage costs. Capital Economics deputy chief economist Ruth Gregory expects further weakness in the housing market, with the recent increase in market interest rates likely to push typical two-year fixed mortgage rates close to 5% in September, compared with 4.8% in July.
Gregory expects house prices to remain broadly flat through the rest of 2026. Her forecast indicates that prices could be around 1.5% higher in the fourth quarter of 2026 than a year earlier, suggesting that the current decline does not necessarily point to a prolonged nationwide fall in property values.
There is, however, a difference between the major house price indices. Nationwide Building Society reported 1.6% annual house price growth in August, along with a 0.2% monthly increase. This contrasts with the decline recorded by Lloyds and highlights differences in methodology and the mortgage data used by individual lenders.
Lloyds' index was previously published under the Halifax brand. From July, it was renamed the Lloyds House Price Index, although Lloyds said the methodology remains unchanged and the index continues to use mortgage data from both Halifax and Lloyds.
Regional performance has also remained uneven. Recent reporting on the Lloyds figures showed stronger annual price growth in Northern Ireland, Scotland and Wales, while southern England faced declines. Northern Ireland recorded the strongest annual increase at 6.9%, followed by Scotland at 3.5% and Wales at 0.6%. The South East recorded a 1.6% decline and Greater London fell 1.5%.
The latest official figures from the Office for National Statistics had shown a 2.0% annual increase in UK house prices in the 12 months to June, slowing from 3.0% in the year to May. This suggests that the broader market had already been losing momentum before the Lloyds index recorded its first annual decline.
The housing market is also facing pressure from higher mortgage rates. Recent market data showed fixed mortgage rates moving above 5.6%, compared with levels below 5% earlier in the year. Higher financing costs have reduced affordability for prospective buyers and contributed to weaker demand.
Source Reuters
13th Nov, 2026
13th Nov, 2026

4th Nov, 2026
4th Nov, 2026
3rd Nov, 2026
2nd Nov, 2026
30th Oct, 2026

25th Oct, 2026
Advertisement








 Facebook
 Whatsapp

