Advertisement






The Gulf conflict has disrupted global supply chains, pushed...
REITs have changed the way commercial real estate is owned a...
What really powers the cloud? Behind every Google search, A...
What really powers the cloud? Behind every Google search, A...
Luxury real estate is one of the most talked-about segments ...
India’s semiconductor market is projected to expand from nearly USD 64 billion in 2026 to USD 200 billion by 2035, according to an EY–India Electronics and Semiconductor Association (IESA) report titled Semicon India 2.0: From capacity creation to ecosystem leadership. Unveiled at SEMICON India 2026, the report identifies consumer electronics, automotive and industrial applications as the largest demand segments, accounting for 30%, 16% and 15% of the market, respectively. Semiconductor imports rose from USD 5.7 billion in FY17 to USD 30.3 billion in FY25, representing a compound annual growth rate of 23%. India also accounts for nearly 20% of the world’s chip design engineers. The report highlights advanced packaging, compound semiconductors, photonics and chip-to-system integration as potential growth areas, while calling for coordinated policy, infrastructure, talent development and industry partnerships to strengthen domestic manufacturing and innovation.
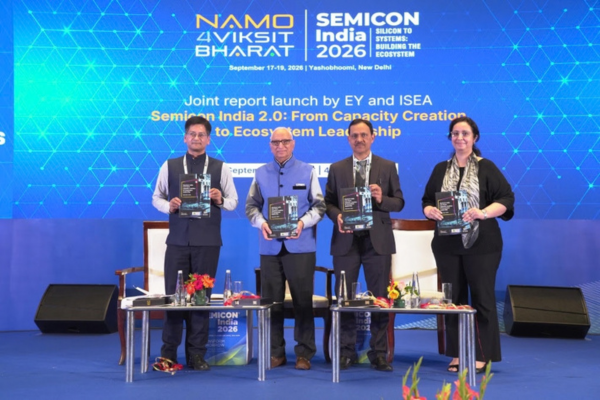
India’s semiconductor market is projected to grow more than threefold, from nearly USD 64 billion in 2026 to USD 200 billion by 2035, according to a report jointly prepared by EY and the India Electronics and Semiconductor Association (IESA). Titled Semicon India 2.0: From capacity creation to ecosystem leadership, the report was unveiled at SEMICON India 2026 and outlines opportunities to expand domestic manufacturing, innovation and supply-chain capabilities.
Consumer electronics currently accounts for 30% of India’s semiconductor market, making it the largest demand segment, followed by automotive applications at 16% and industrial applications at 15%. Artificial intelligence, data centres, telecommunications, electric mobility and advanced manufacturing are also emerging as additional sources of demand.
The report highlighted the scale of India’s dependence on imported semiconductors. Imports increased more than fivefold from USD 5.7 billion in FY17 to USD 30.3 billion in FY25, registering a compound annual growth rate of 23%. It identified the expanding domestic market as an opportunity to increase local manufacturing and innovation.
India’s existing design capabilities provide another foundation for developing the sector. The country accounts for nearly 20% of the world’s chip design engineers, offering a talent base that could support semiconductor manufacturing, indigenous design and commercialisation.
Ashok Chandak, president of IESA, said India could combine its engineering workforce, electronics demand, design capabilities and emerging manufacturing capacity with partnerships aimed at building resilient global supply chains. He identified execution, innovation, technology commercialisation, indigenous intellectual property, specialised talent and ecosystem development as priorities for the next phase of growth.
Aisha Ali Hussaini, partner and semiconductor tax leader at EY India, pointed to the expansion of the electronics industry as evidence of the broader manufacturing base. Electronics production increased sixfold from INR 1.9 lakh crore in FY15 to INR 11.3 lakh crore in FY25. Electronics manufacturing and exports grew sevenfold and elevenfold, respectively, over the same period.
She said the priority was to translate this expansion into greater domestic semiconductor value addition. A predictable fiscal and regulatory environment, closer alignment between central and state policies, and targeted support for emerging technologies could improve project viability and accelerate commercialisation. Collaboration between industry, government and academia would also be important in expanding manufacturing, advanced packaging and other parts of the semiconductor value chain.
Policy, infrastructure and emerging opportunities
The EY–IESA report recommends aligning state semiconductor policies with the broader scope of Semicon 2.0, developing integrated manufacturing clusters with shared infrastructure, and introducing dedicated talent-certification programmes covering chip design, fabrication and advanced packaging.
It also identifies advanced packaging, compound semiconductors, photonics and chip-to-system integration as areas with growth potential, supported by India’s design capabilities, rising electronics and AI demand, and developing manufacturing base.
Realising these opportunities, the report states, will require coordinated action. Investors will consider policy certainty, cluster readiness and implementation timelines, while companies will need stronger partnerships with suppliers, academic institutions and technology owners to develop local capabilities. Policymakers, meanwhile, will need to streamline approvals and maintain long-term support for research, talent and supplier development.
The report’s central focus is the transition from creating semiconductor capacity to developing a broader ecosystem spanning manufacturing, design, technology commercialisation and supporting supply chains.

17th Nov, 2026

17th Nov, 2026


17th Nov, 2026




17th Nov, 2026


17th Nov, 2026
Advertisement








 Facebook
 Whatsapp

