Advertisement






The Gulf conflict has disrupted global supply chains, pushed...
REITs have changed the way commercial real estate is owned a...
What really powers the cloud? Behind every Google search, A...
What really powers the cloud? Behind every Google search, A...
Luxury real estate is one of the most talked-about segments ...
India’s commercial real estate sector is seeing a broader mix of financing as office, logistics, data centres, healthcare and other income-generating assets require capital across development and operating stages. Institutional investment in Indian real estate reached USD 8.5 billion in 2025, with offices accounting for 54%, while offices represented more than 40% of investment inflows in the first half of 2026. Private credit is also becoming more established, with EY reporting USD 3.5 billion of private credit investments in India during H1 2026, 35% of which was deployed in real estate. Domestic funds accounted for 74% of private credit deal value during the period, indicating a growing domestic capital base alongside traditional lenders, institutional equity and alternative investment funds.
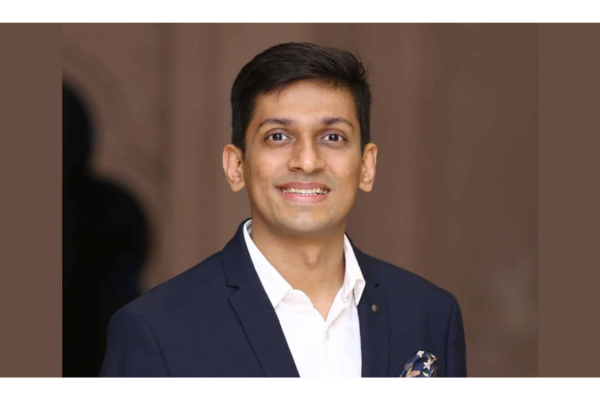
India’s commercial real estate sector is seeing increasing demand for varied forms of capital as office, logistics, data centre and other income-generating assets expand, according to Sudarshan Lodha, Co-founder and CEO of Strata. The financing requirement spans land acquisition, promoter equity, construction, acquisitions and last-mile funding, with each stage carrying different risk profiles, timelines and security requirements.
Traditional bank lending is expected to remain an important component of the financing ecosystem, but conventional structures may not suit every requirement. Private credit, alternative investment funds (AIFs), institutional equity and structured financing are consequently providing additional sources of capital for projects at different stages of their development and operating cycles.
Institutional investment in Indian real estate reached USD 8.5 billion in 2025, with office assets accounting for 54% of total investment. During the first half of 2026, offices continued to account for more than 40% of investment inflows. The level of institutional participation indicates the scale of capital being deployed into the sector and the increasing requirement for financing structures suited to different asset characteristics.
Private credit is also expanding beyond its earlier association with distressed or emergency funding. EY reported USD 3.5 billion of private credit investments in India during H1 2026, with real estate representing 35% of total deal value. Such financing can be deployed towards acquisitions, construction, refinancing, expansion and asset-level requirements, including project financing and HoldCo funding.
Senior secured and mezzanine structures can be tailored to an asset’s cash flows and repayment capacity, particularly where the timing of funding and execution is important. A completed leased asset seeking refinancing, for instance, can have financing requirements that differ from those of a project still under construction.
The diversification of commercial real estate is adding another layer to these requirements. While offices remain a major institutional investment segment, logistics, data centres, GCC-led developments, flexible workspaces and healthcare assets are attracting investor interest. Differences in development periods, tenant profiles and operating characteristics mean that financing structures may need to account for the specific nature of each asset.
Capital is also increasingly being directed towards assets with visible cash flows, quality tenants, stronger governance and institutional-grade characteristics. Alongside development and capital appreciation, investors are examining long-term income generation and operational quality, particularly in leased commercial properties.
Domestic investors and fund managers are becoming a significant part of this ecosystem. According to EY, domestic funds accounted for 74% of private credit deal value and nearly 79% of deal count in H1 2026. A deeper domestic capital base could support specialised funds focused on particular asset classes, locations and stages of the real estate lifecycle.
As alternative capital becomes more established, underwriting, due diligence, cash-flow visibility and security structures are gaining importance. Location, tenant quality, developer capability, asset fundamentals and exit visibility remain key considerations when structuring financing. The emerging capital ecosystem is therefore increasingly centred on matching the form and terms of funding with the underlying asset and its stage of development.
Disclaimer:
The views, opinions, and information expressed in this article are solely those of the author and do not necessarily reflect the views of Prop News Time. The content has not been independently verified or endorsed by Prop News Time. Readers are advised to exercise their own discretion and seek professional advice if required.

17th Nov, 2026

17th Nov, 2026


17th Nov, 2026




17th Nov, 2026


17th Nov, 2026
Advertisement








 Facebook
 Whatsapp

